

September asked a lot of Indonesian investors: the IHSG fell 6.96%, the Fed raised rates again, and foreign investors withdrew Rp 10.2 trillion from Indonesian Equities. Here is what moved markets, how AMP and our funds performed, and how we are positioned for October.
Market Highlights
The IHSG returned -6.96% to close at 6,071, while the INDOBeX returned -0.26%. Foreign investors sold Rp 10.2 trillion of Indonesian Equities after net inflows in July and August, taking year-to-date outflows to Rp 81.9 trillion with the IHSG down 29.79%.
Suahasil Nazara replaced Purbaya Yudhi Sadewa as Finance Minister on 14 September, and the DPR passed the 2027 State Budget with a deficit target of 2.4% of GDP.
Government bond yields rose, with the 5Y up 12 bps to 7.00% and the 10Y up 11 bps to 7.14%, while the INDON 3Y rose 63 bps to 5.28%. The Rupiah weakened from 17,720 to 17,870, and Bank Indonesia held the BI-Rate at 5.75% in Governor Destry Damayanti’s first meeting, having already hiked in June.
The Fed raised rates by 25 bps to 3.75%–4.00% on 16 September, with most members projecting another hike this year. Brent crude held around USD 100 a barrel amid renewed US–Iran tensions. The 10-year US Treasury yield rose from 4.75% to 5.28%. This narrowed the premium on Indonesian bonds and weighed on the Rupiah.
How Did AMP Perform
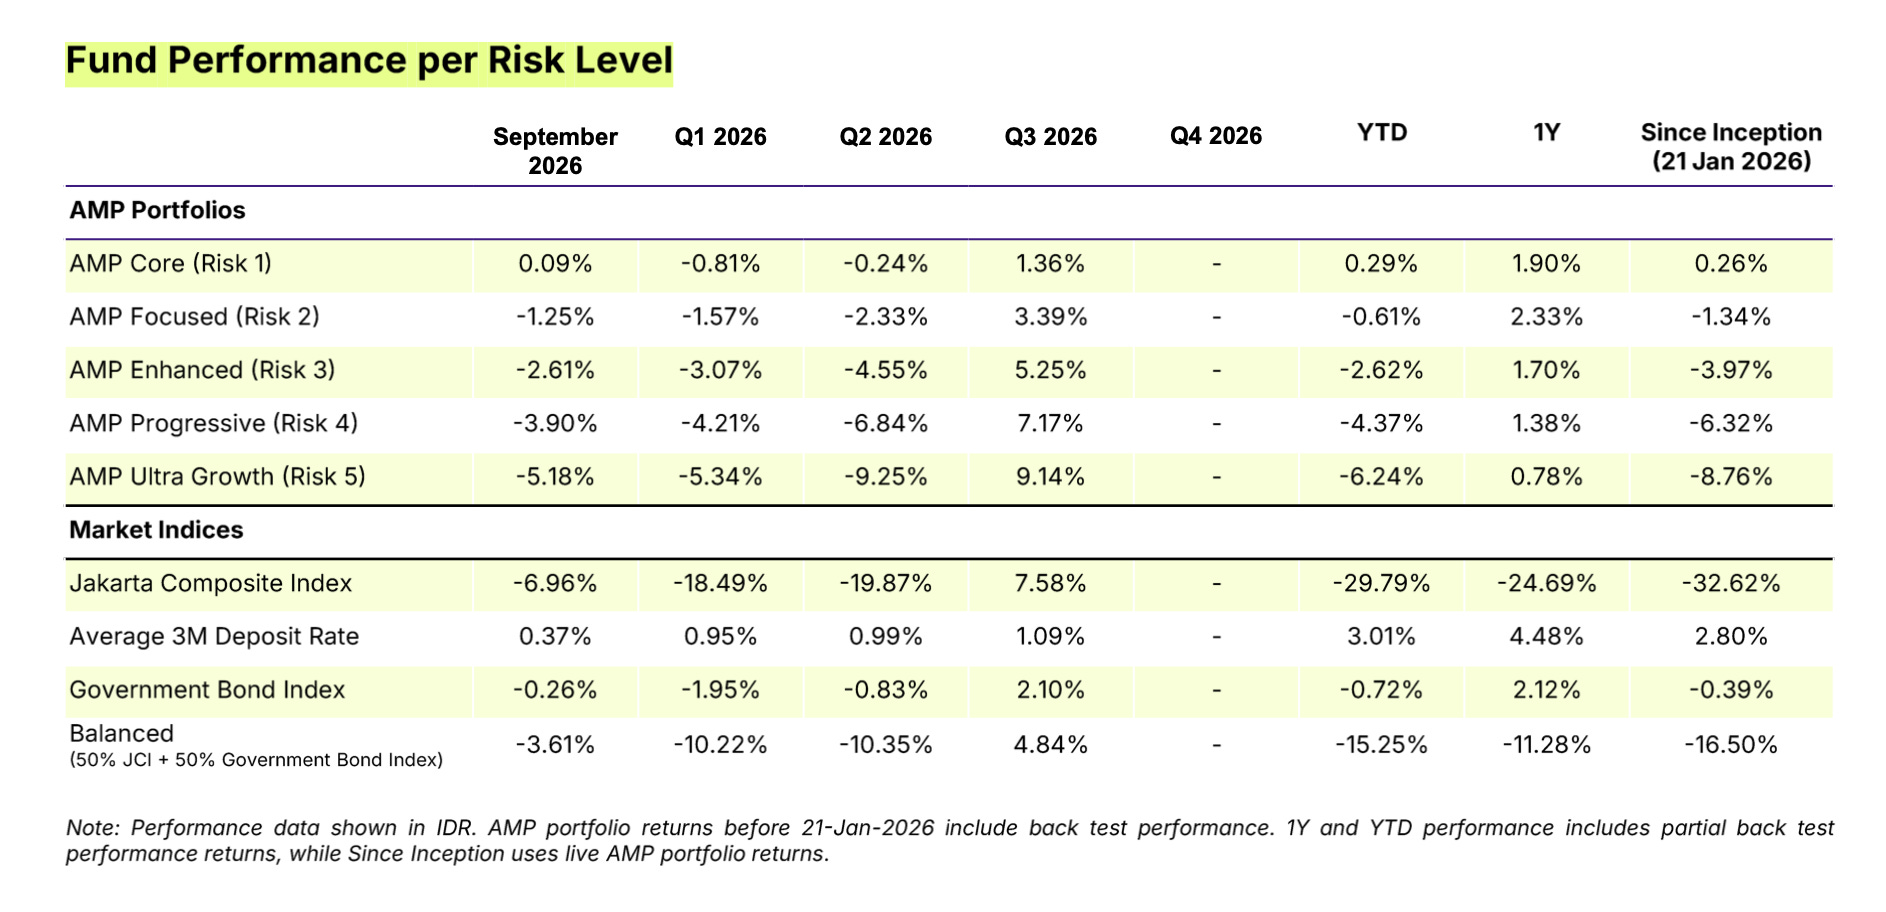
Risk Level 1 returned 0.09%, as its higher cash weighting limited the impact of easing government bond prices.
Risk Levels 2 through 5 returned between -1.25% and -5.18%, in line with each tier’s Equity weighting as the IHSG fell 6.96%. Because we had raised Equity entering September, each tier carried more Equity than its strategic weight into the decline.
How Did the Funds Perform
All our funds posted negative returns in September except Simpan Cash Fund and Simpan Cash Syariah Fund. Simpan Cash Fund also outperformed its benchmark, while the Sustainable Equity, Bond, Balanced, Cash Syariah and Dollar Bond Funds finished behind theirs. The main driver was the Fed’s hike and its signal of one more by year-end, which set off a repricing of global assets.
Equities. Our equity portfolios posted a negative month and underperformed the IHSG, with commodities holdings the main detractors, led by BRPT, CUAN and ADRO. We exited United Tractors (UNTR) to realise profits, and Darma Henwa (DEWA) after a deep price correction, as new regulations from the Minister of Energy and Mineral Resources on selecting mining contractors changed sentiment toward the sector.
Fixed Income. Government bonds weakened slightly, with the 10Y yield touching 7.20% before closing at 7.14%, though Rupiah bonds still held up better than US Treasuries. The Dollar Bond Fund trailed as rising yields lowered bond prices, while its benchmark accrues yield without price changes.
Key Trades of the Month
Equities: exited UNTR and DEWA. We exited United Tractors (UNTR) to realise profits, and Darma Henwa (DEWA) after selling pressure drove a deep price correction. New regulations from the Minister of Energy and Mineral Resources on selecting mining contractors for concessions also changed sentiment toward the sector.
Fixed Income: duration kept below benchmark. Our Fixed Income funds kept an average duration of 4.95 years, below benchmark, and performance remained resilient despite the volatility. Into October, we stay cautious on duration and favour mid- and short-tenor bonds for their risk-return profile at current yields.
Outlook & Positioning
Bank Indonesia is holding rates while the Fed hikes, having moved early in June, and the Rupiah has absorbed the pressure. Rupiah bond yields look attractive, but their premium over US Treasuries has narrowed, so we prefer Indonesia’s US Dollar bonds through the Simpan Dollar Bond Fund. In Equities, lower prices offer a good entry point into companies with solid fundamentals.
For October:
Risk Levels 2–5: adding Equity gradually, funded evenly from our Cash and Fixed Income Funds.
Risk Level 1: increasing Fixed Income and reducing Cash, with government bond yields of 6.79%–7.14% against 4.48% on three-month deposits. Cash remains the larger weight while further Fed hikes are possible.
The main risk to both positions is the FOMC decision on 27–28 October.
Key watchpoints: FOMC (27–28 October), Bank Indonesia (20–21 October), the Rupiah, oil prices amid US–Iran tensions, Indonesia’s Q3 GDP, and the MSCI November review.
Thank you for your continued trust.